Many SMSF clients want to understand how the new Division 296 tax might work. We have found that it can be difficult to succinctly communicate this in practice.
However, we hope we can provide a helpful tool! The tools are the following formulas.
These formulas provide a succinct summary of how the new tax might be calculated. Advisers might wish to use them as an ‘educational aide’ when discussing the new tax with clients.
We also link several prior articles that provide an outline of the Div 296 tax that is proposed to commence from 1 July 2026. Broadly, this new tax will, when enacted, apply to superannuation members with more than $3 million in superannuation from 1 July 2026.
Please note the legislation is still draft form and may change before being finalised. Naturally, seeking expert and up to date advice is recommended.
How To Calculate The Tax For FY2027
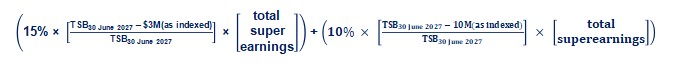
HOW TO CALCULATE THE TAX FOR FY2028 & ONWARDS
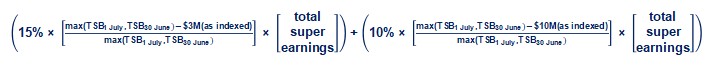
POINTS TO REMEMBER
When using the formulas, remember:
- ‘TSB’ means total superannuation balance.
- If a person’s TSB is $3 million or less, they pay no Division 296 tax.
- If a person’s TSB is $10 million or less, ignore the second brackets in each of the formulas above.
- If a person exceeds the $3 million TSB in respect of a financial year (FY) and they have some total super earnings, they will be liable for Division 296 tax for that FY. However, if they exceed the $3 million TSB and their total super earnings are nil or less, they will not pay any Division 296 tax for that FY.
- An additional nominal 15% Div 296 tax will apply reflective of the proportion of the member’s TSB that exceeds $3 million. A further nominal 10% Div 296 tax will apply reflective of the proportion of the member’s TSB that exceeds $10 million. This is reflected in the formulas above.
- If a person is liable for Div 296 tax, they will be entitled to a release authority issued by the ATO to withdraw money from superannuation to pay this tax (even if they have not attained 60 years and have not retired from gainful employment).
- A person’s total super earnings essentially mean the total of the portion of each of their super fund’s taxable income that is attributable to them. The taxable income will have certain adjustments. The key adjustments are subtracting concessional contributions from the fund’s taxable income attributed to them and adding back net exempt current pension income.
- When calculating total super earnings, SMSFs will be able to apply a CGT adjustment. Essentially, the CGT adjustment is that the first element of an asset’s cost base is taken to be its market value as at the end of 30 June 2026.
- As noted above, this is not law. We are only summarising the proposals based on thedraft bills for the government’s Better Targeted Super Concessions policy. You can view that material at: https://consult.treasury.gov.au/c2025-726362
EXAMPLE
Peter is the sole member of the Pumpkin SMSF. This is the only superannuation fund of which he is a member.
As at the end of 30 June 2026, the Pumpkin SMSF’s sole assets were a bank account ($1 million) and real estate. The Pumpkin SMSF purchased the real estate many years ago for $2.5 million. The real estate’s market value at the end of 30 June 2026 was $4 million and Peter’s TSB was $5 million.
During FY2027, the Pumpkin SMSF:
- sells the real estate for $4.5 million;
- earns $40,000 of interest; and
- receives $30,000 of concessional contributions.
At the end of FY2027, Peter’s TSB is $5.57 million. The Pumpkin SMSF chooses to apply the CGT adjustment.
Peter’s total super earnings for FY2027 are likely to be $373,333, calculated as: ($4.5 million – $4 million) x ⅔ + $40,000
Peter’s Division 296 tax for FY2027 is likely to be:
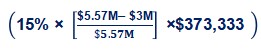
= $25,838.42
This is a fairly simple example — yet, it becomes complex quite quickly to manually calculate.
Nevertheless, we feel the quickest way for a client to understand this proposed new tax is with the formulas above.
Related articles/webinars:
- Pre-30 June 2026 tips to plan for new Div 296 ($3M+) tax (webinar)
- Division 296: revised $3m+ super tax
- Revised Division 296 super tax from 1 July 2026
* * *
This article is for general information only and should not be relied upon without first seeking advice from an appropriately qualified professional. The above does not constitute financial product advice. Financial product advice can only be obtained from a licenced financial adviser under the Corporations Act 2001 (Cth).
Note: DBA Lawyers presents monthly online SMSF training. For more details or to register, visit www.dbanetwork.com.au or call 03 9092 9400.
For more information regarding how DBA Lawyers can assist in your SMSF practice, visit www.dbalawyers.com.au.
By Bryce Figot, Special Counsel ([email protected]) and Daniel Butler, Director ([email protected]), DBA Lawyers Pty Ltd .
DBA LAWYERS
13 February 2026
